Blog
The Self-Employed Borrower's Black Box
Discover why underwriters reject qualified self-employed mortgage applicants and how MortgageIQ brings automated clarity and transparency to qualifying income calculations.
Blog
Discover why underwriters reject qualified self-employed mortgage applicants and how MortgageIQ brings automated clarity and transparency to qualifying income calculations.
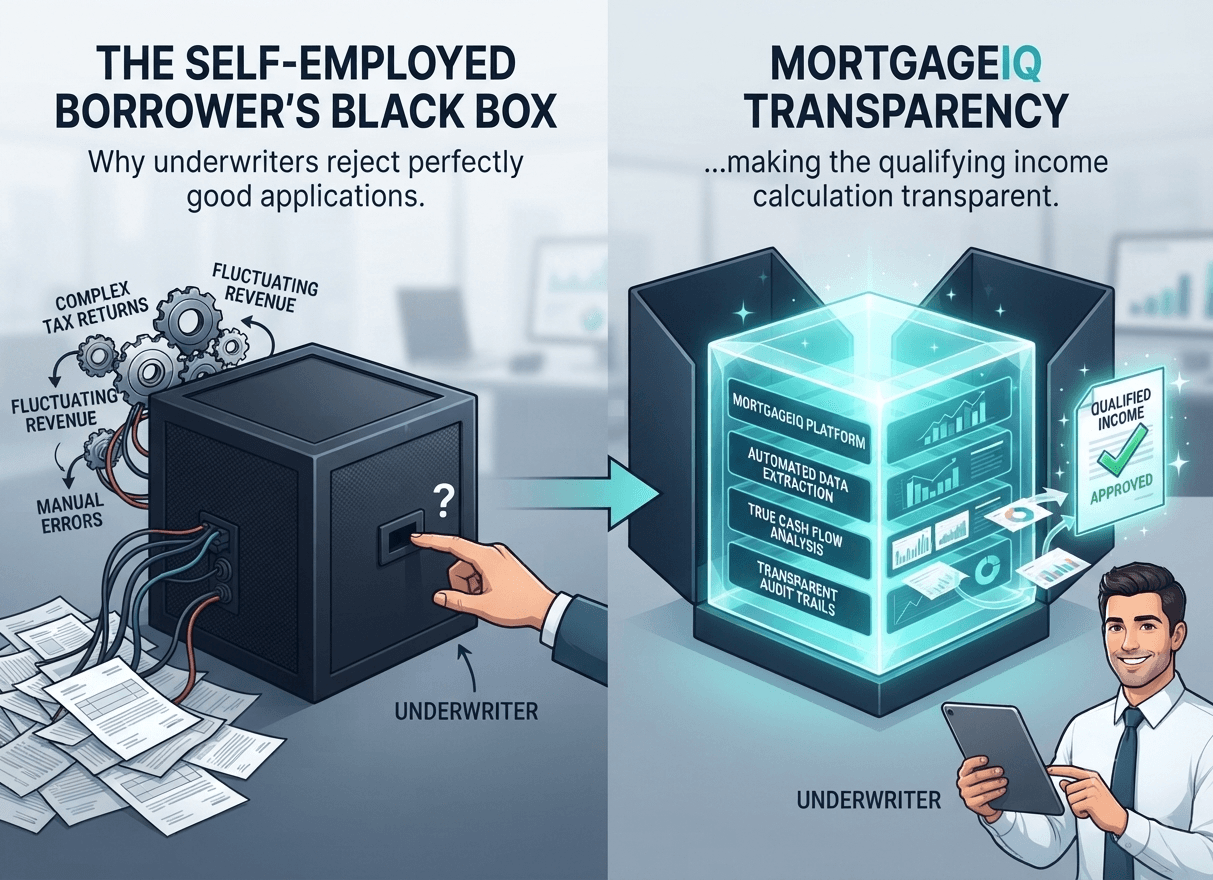
For self-employed professionals, securing a home loan often feels like navigating an opaque maze. While traditional W-2 employees can easily present straightforward pay stubs and standardized tax documents, entrepreneurs, freelancers, and small business owners operate within complex financial structures. Their income is frequently distributed across multiple streams, deductions, depreciations, and business expenses. To institutional lenders and traditional underwriters, this intricate financial picture often resembles a "black box" — an unpredictable system where the final underwriting decision feels completely out of the applicant's hands.
Underwriters are tasked with assessing risk and verifying repayment capacity. However, standard underwriting guidelines are heavily skewed toward traditional wage earners. When evaluating self-employed borrowers, underwriters face several structural hurdles:
The key to overcoming the self-employed borrower's dilemma lies in replacing ambiguity with precision. Lenders and financial institutions need modern tooling that transforms opaque data into clear, defensible insights. Instead of viewing self-employed tax returns as a hurdle, advanced verification systems can systematically parse, analyze, and normalize complex financial documents to reveal the true cash flow of a business.
This is where advanced platforms like MortgageIQ change the paradigm for mortgage lending and self-employed applicants. MortgageIQ bridges the gap between complex business financials and rigid underwriting requirements by bringing radical transparency to the qualifying income calculation.
Securing a mortgage shouldn't be penalized by entrepreneurship. By breaking open the self-employed borrower's black box and replacing manual obscurity with automated clarity, platforms like MortgageIQ empower lenders to say "yes" to qualified business owners with speed, accuracy, and absolute confidence.
Project Manager
See it in your SAP environment
Bring us a document, a process, or a bottleneck. We'll show how Artificio captures, validates, and posts into SAP — then scale from there.
Security & compliance
ISO 27001:2022 certified, SOC 2 Type 2 compliant, GDPR and HIPAA ready. Every agent action is logged, auditable, and runs in isolated environments.