What France's e-invoicing rollout means for companies that still get PDF invoices, and why suppliers far outside France are starting to feel it.
It is a Monday morning in late September, and the accounts payable team at a mid-size packaging manufacturer outside Lyon opens its shared inbox. There are 340 new supplier invoices waiting. Most of them are PDFs. Some come from a steel distributor in Germany, some from a family-run transport firm in Normandy, a few from a software vendor in the United States, and one comes from a large French chemicals group that, a month ago, would have sent exactly the same PDF without a second thought.
That last one is now a problem. The chemicals group is a large enterprise, and since 1 September 2026 it has been required to send its invoices to other French businesses as structured electronic files through an approved platform. A PDF attached to an email no longer meets the rules for that supplier. The other 339 are still perfectly legal, at least for now. Every one of them still has to be opened, read, keyed in, checked and matched by a person.
That is the quiet reality of France's e-invoicing reform. The headlines say the PDF invoice is finished. The inboxes say something else. This article covers what changed on 1 September, which PDF invoices will keep arriving and for how long, why suppliers outside France are feeling the pressure, and what finance teams can do about the pile in the meantime.
What actually changed on 1 September 2026
We checked the dates against the French government's own announcements before writing this, because the reform has slipped before. It was first meant to start in July 2024 and was pushed back. This time the date held. The French Ministry of the Economy confirmed on 1 September 2026 that business-to-business e-invoicing had officially come into force.
Two obligations started that day. Every business established in France and registered for VAT must now be able to receive electronic invoices, whatever its size. The government puts that at more than 10 million economic actors, from global groups down to sole traders. On top of that, large enterprises and mid-size companies (known in France as ETIs) must now issue their invoices electronically and start sending transaction data to the tax authority. The French call this second duty e-reporting.
The size thresholds apply per legal entity, not per group. A large enterprise has 5,000 or more employees or turnover of at least €1.5 billion. An ETI sits roughly between 250 and 4,999 employees, or between €50 million and €1.5 billion in turnover. Everyone smaller, including SMEs and micro-businesses, gets one more year. Their obligation to issue e-invoices starts on 1 September 2027.
The government has also softened the landing. It announced that businesses running into genuine difficulties will not face sanctions during the start-up phase, and that this period of tolerance lasts until the end of 2026. That is an administrative grace period, not a postponement. The dates have not moved. The tolerance is aimed at companies that are visibly working toward compliance, not at those waiting to see what happens.
When the grace period ends, the penalties are real, and they are higher than most people think. France's 2026 finance law, passed in February, raised them before launch. Failing to issue an invoice electronically now costs €50 per invoice, up from the €15 that many English-language guides still quote, with a cap of €15,000 per calendar year. A missing e-reporting transmission costs €500, up from €250. A company that has not appointed a platform to receive invoices first gets a formal notice. If it has not fixed things within three months, it pays €500, then €1,000 for each further quarter the problem continues.
Put that in everyday terms. A supplier that sends 300 non-compliant invoices in a year hits the annual invoicing cap. That is roughly one bad invoice for every working day.
Why a PDF no longer counts as an invoice (for some senders)
Most people picture an invoice as a document. France now treats it as a set of data.
Under the new system, an invoice does not travel straight from seller to buyer by email. The seller submits it to its own approved platform, called a Plateforme Agréée or PA. That platform looks up the buyer in a national directory using the buyer's SIREN number, finds the buyer's registered receiving address, and hands the invoice to the buyer's platform. At the same time, a subset of the invoice data goes to the tax authority. People in the industry call this the five-corner model, because five parties take part in the flow instead of two. By the summer of 2026 the official list of approved platforms had passed 100 names.
The invoice must be in one of three accepted formats. UBL and CII are pure XML files that software can read but people cannot. Factur-X is the one that confuses everyone because it looks like a PDF. It is a PDF/A-3 file with the structured XML data embedded inside it, so a person can open it and read it while a system reads the data underneath. A normal PDF exported from Word or an accounting package has no data layer. To a computer, it is a picture of an invoice.
A boarding pass is a good comparison. The printed pass shows your name, flight and seat. The barcode is what the gate scanner actually reads. Factur-X is the boarding pass with the barcode. A plain PDF is a photograph of a boarding pass with the barcode cut off. It looks right to a human, and the gate still will not open.
The data layer also brings something a PDF never had, which is a status. Each e-invoice now carries a lifecycle that both sides can see. It has been deposited, it has been rejected for a technical fault, it has been refused by the buyer, it has been paid. Some of these statuses are mandatory and flow back to the tax authority. A PDF sitting in an inbox has none of this. Nobody outside the accounts payable team knows whether it has been seen, disputed or paid.
The PDF tail: three streams that are not going away
Here is the part that gets lost in most of the coverage. The reform does not stop PDFs from arriving. It stops certain senders from sending them, on a staggered schedule, and it leaves other senders untouched.
For a large or mid-size French company, the incoming invoice pile now splits into three streams.
The first stream is French large enterprises and ETIs. Since 1 September they should be sending structured e-invoices through the network. Many are, and many are not quite there yet. Industry surveys in the weeks before launch found that roughly a quarter of France's largest billers still had not finalised their choice of platform, and one of the country's biggest utilities said publicly that it had struggled to find enough operators ready to receive its invoice flows. During the tolerance period, expect a mix of proper e-invoices, Factur-X files sent the old way by email, and plain PDFs from suppliers who are still catching up.
The second stream is French SMEs and micro-businesses. They make up most suppliers by count for almost any French company, and they are allowed to keep sending paper and PDF invoices until 1 September 2027. For the next eleven months, this stream stays mostly PDF, and it is usually the largest of the three.
The third stream is foreign suppliers, and it has no fixed end date. The French e-invoicing obligation applies to businesses established in France. A German distributor, an Italian component maker, an Indian IT services firm or an American software company with no French establishment sits outside the e-invoicing half of the reform. Their PDFs remain valid. Inside the EU, that only changes when the VAT in the Digital Age package (ViDA) brings mandatory e-invoicing for cross-border B2B trade from 1 July 2030. For suppliers outside the EU, nothing on the calendar ends it at all.

Put the three streams side by side and the picture is clear. France has not ended PDF invoices for French buyers. It has made them unevenly legal. Some are now out of line with the rules, most are fine for another year, and a meaningful share will stay fine for years. The finance team has to handle all three at once, and it has to know which invoice belongs to which stream.
Why suppliers outside France feel it too
If foreign suppliers are out of scope, why are they feeling the pressure? There are three reasons, and none of them needs a change in French law aimed at them.
The first reason is the buyer's own reporting duty. From 1 September 2027, every French business, whatever its size, must e-report certain purchases that do not travel through the domestic e-invoicing network. That includes goods bought from other EU countries and services bought under the reverse-charge rule. In plain terms, when a French company buys from a German supplier and accounts for the VAT itself, it will have to send data about that purchase to the tax authority through its platform. The 2026 simplification package trimmed this so that line-by-line detail is no longer needed for incoming cross-border invoices. Summary data still has to be reported, and it still has to come from somewhere. If the supplier sends a PDF, the French buyer has to pull the numbers out of it.
The second reason is commercial. French buyers have spent real money on platforms, integration and new processes. Their accounts payable teams are being measured on how much of the invoice flow comes in clean. A buyer whose French suppliers now send structured data will quickly notice the foreign suppliers who do not. Procurement teams are already writing structured-invoice requirements into supplier onboarding and contract renewals. Nobody forces a supplier in Stuttgart or Pune to send Factur-X. The customer just starts asking, and the supplier who makes life easier tends to get paid sooner.
The third reason is VAT registration. A foreign company registered for French VAT but without a French establishment avoids the e-invoicing work, but it can still owe e-reporting on its French-taxable sales, and those obligations begin on 1 September 2027. That company will need a contract with an approved platform just to send its data, even though it never issues a French e-invoice. And if a French warehouse, a local service team or a manufacturing arrangement could count as a fixed establishment for VAT purposes, the company may be fully in scope. That question deserves a proper answer from a VAT adviser, not an assumption.
France is also not acting alone. Germany has required businesses to be able to receive e-invoices since January 2025, with issuing obligations phasing in from 2027. Belgium made structured B2B e-invoicing mandatory in January 2026. Other European countries are on their own timetables, and ViDA ties them together in 2030. A supplier that sells into Europe from anywhere in the world will be asked for structured invoices by one customer after another. France is simply the largest and most visible market to switch on this year.
The four fields that trip up a PDF
Even when a PDF is still legally acceptable, it often falls short on content. Since 1 January 2025, French invoices between businesses have had to carry four extra pieces of information. Most invoice templates built outside France do not include them, and plenty of French SME templates still miss them.
The first is the customer's SIREN number, the nine-digit identifier of the French legal entity. It is the key the tax authority uses to match records, and the directory uses it to route invoices. The second is the delivery address of the goods, when it differs from the customer's billing address. The third is the category of the transaction, which states whether the invoice covers goods only, services only, or both. The fourth is a note that the supplier has chosen to pay VAT based on invoices rather than on payments, where that option applies.
The category flag sounds like paperwork, but it carries weight. In France, VAT on goods falls due on delivery, while VAT on services generally falls due when the customer pays. An invoice for a packaging machine plus two days of installation is a mixed invoice, and only the service part feeds payment reporting. A PDF that simply says "Machine and installation, €84,000" gives the buyer no way to split that without someone reading it and deciding.
Here is a concrete case. Our Lyon manufacturer receives a PDF from its Normandy transport firm for €6,420. The PDF shows the carrier's own SIREN but not the customer's. It shows the head-office billing address but not the warehouse in Villefranche where the pallets were actually delivered. It has no category at all. Nothing about it breaks the law today, because the carrier is an SME. When the carrier's own deadline arrives next September, that same invoice will have to carry all of this in structured form. Until then, the buyer's team keys and checks it by hand, every single time.
One PDF invoice, followed from inbox to ledger
It helps to follow a single invoice through two versions of the same accounts payable team.
In the first version, nothing much has changed since August. A PDF from the German steel distributor lands in the shared inbox. A clerk opens it and reads the supplier name, the invoice number, the date, the net amount of €18,750 and the reverse-charge note. She keys these into the ERP, matches them against the purchase order and the goods receipt, and sends a query when the invoice says 12 tonnes and the receipt says 11.6. The invoice waits in a queue for four days. Nobody captures the data the company will need for e-reporting in 2027, because nobody has asked for it yet. Multiply that by several hundred invoices a week and the team spends most of its time typing.
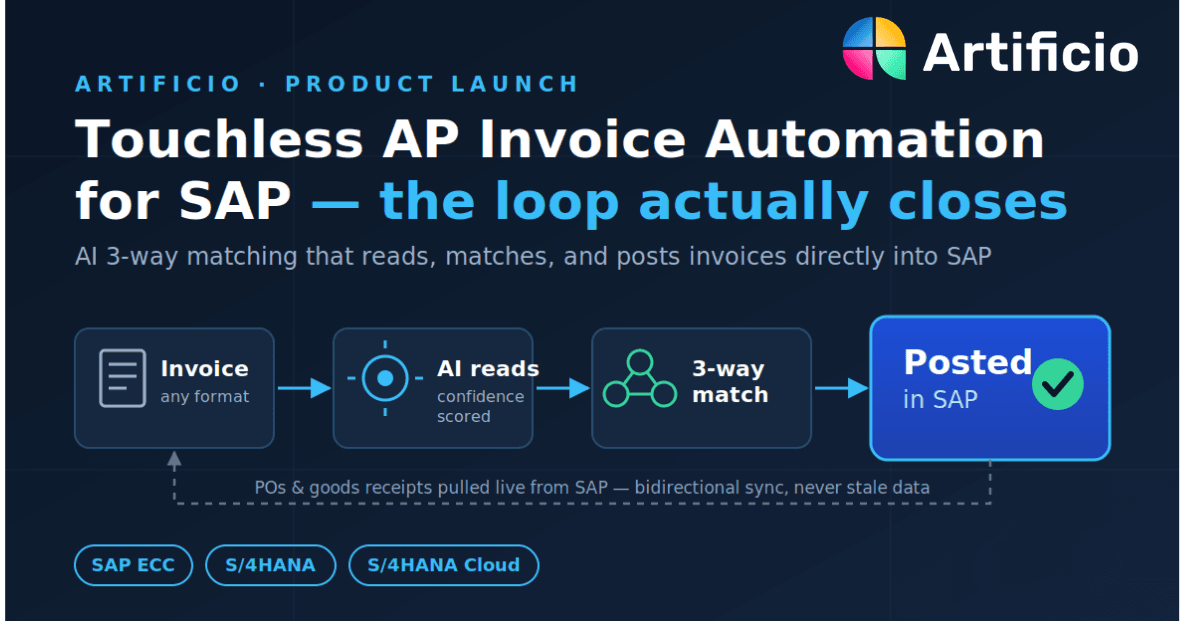
In the second version, the same PDF lands in the same inbox. An AI agent picks it up as soon as it arrives. It recognises the document as an invoice rather than a delivery note or a statement. It reads the supplier, the amounts, the VAT treatment and each line, then checks them against the purchase order and the goods receipt. It spots the 0.4-tonne gap and sends the invoice to the buyer responsible, with the difference already highlighted. It recognises a purchase from another EU country under reverse charge and tags the summary data for the e-reporting feed that begins next year. It checks the four French mentions and records what is missing. The clean, structured record goes into the ERP. A person only looks at the exception.
The difference between these two teams is not whether they receive PDFs. Both do. It is whether the PDF ends its journey as a flat image in an archive or as structured data the company can report on, reconcile and act on.
Where AI agents fit, and where they do not
This is the gap Artificio was built for. Artificio uses AI agents rather than traditional OCR templates to read business documents. A template-based OCR tool has to be told where the invoice number sits on each supplier's layout, and it breaks when the supplier redesigns its invoice. An AI agent reads an invoice the way an experienced clerk does, by understanding what each piece of text means. A new supplier or a new layout does not mean a new template.
For a French finance team, that means all three PDF streams can become structured data on the way in. Invoices from French SMEs, from foreign suppliers and from large French suppliers still catching up can be read, classified, checked against purchase orders and against the French mandatory fields, and passed to the ERP in the same shape as the e-invoices arriving through the network. Suppliers who send clean data and suppliers who send PDFs end up in the same queue, handled the same way.
It matters just as much to be clear about what an AI document agent is not. It is not an approved platform. It does not transmit invoices through the French network, and it does not file e-reporting on anyone's behalf. That job belongs to a Plateforme Agréée on the official DGFiP list, and every French business needs one. Document agents sit in front of that platform and the ERP, handling everything that does not arrive as clean data.
The same approach works on the sending side. A French SME facing the 2027 deadline, or a foreign supplier whose French customers have started asking questions, can pull structured data out of the invoices it already produces and hand it to a platform, instead of rebuilding its whole billing system in a hurry.
A PDF-to-data layer also stays useful for longer than people expect. The French SME stream closes in September 2027. The EU cross-border stream closes in July 2030. The non-EU stream never closes. And plenty of the documents that travel with an invoice, from delivery notes and customs paperwork to credit notes, supplier statements and remittance advice, will keep arriving as PDFs whatever happens to tax rules.
A 90-day plan for teams still buried in PDFs
If your team is in France or sells to French customers, the realistic goal for the rest of 2026 is not a perfect system. It is being reachable, reading what arrives, and holding a written plan for the rest. That is also exactly what the tolerance period rewards.
Confirm your platform and your directory entry. Every French entity needs an approved platform for receiving invoices, and that platform registers your receiving address in the national directory. Check that the entry exists and that it points where you expect. Check your platform's status on the official DGFiP list rather than on a vendor's copy of it.
Sort your supplier base into the three streams. Pull a year of supplier invoices and tag each supplier as a French large company or ETI, a French SME, or a foreign supplier. This shows you how much of your volume should already be structured, how much will switch next September, and how much will stay PDF for years.
Chase the first stream now. Large French suppliers still sending plain PDFs are out of line with the rules. A polite note asking them to send through the network is fair, and the tolerance period gives both sides room to fix it before fines apply.
Automate the second and third streams. PDFs from SMEs and foreign suppliers will not disappear on your timeline. Put document intelligence in front of your ERP so these invoices become structured data on arrival, with the French fields checked and exceptions routed to the right person.
Start capturing e-reporting data today. Buyer-side e-reporting for EU purchases and reverse-charge services starts on 1 September 2027. Tag those invoices now and run a practice reporting period well before one counts.
If you supply French customers from abroad, get ahead of the ask. Find out whether your customers want Factur-X, UBL or a portal upload. Add the customer SIREN, the delivery address and the transaction category to your invoice template. Check whether your French VAT registration or local operations bring you into e-reporting in 2027.
Write down what is not ready. During the tolerance period, documented good faith counts for more than a half-finished integration.
The PDF is not dead. It just cannot be the end of the story.
France's reform is often described as the end of the PDF invoice. That is not quite right. What has ended is the idea that a PDF is where an invoice's life can stop. For large and mid-size French companies, an invoice is now a data record with a lifecycle, a status and a copy at the tax authority. For their suppliers in France and abroad, the pressure to send that data cleanly will only grow as the SME deadline arrives in 2027 and the EU follows in 2030.
The companies that come through this well will not be the ones that receive the fewest PDFs. They will be the ones that stop letting a PDF sit as a picture in an inbox. Every invoice that arrives, in whatever format, becomes structured data within minutes, gets checked against the French rules, and lands in the ledger and the reporting feed without anyone retyping it.
Our Lyon manufacturer will still open an inbox full of PDFs next Monday, and probably for a few years after that. The real question is whether its team spends the week typing, or spends it on the dozen invoices that actually need a human decision.